Debt Management · DM-1
DM-1 | A loan at 6%: refinance now or wait until maturity?
CDL · PRACTICAL CASE STUDIES · ILLUSTRATIVE EXAMPLE
Debt Management · One loan, alternative structures and two funding-cost stress tests.
A manufacturing company has a €900,000 loan with a fixed interest rate of 6%. Interest is paid quarterly, and the entire principal falls due in nine months. The company expects to keep using that €900,000 in the business, so it plans to replace the loan rather than repay it from its own cash.
The finance director can retain the existing contract until maturity, refinance earlier or lock in a rate for longer. The question goes beyond finding a lower headline rate: which combination of timing, tenor and interest-rate structure produces the lowest conditional cost over the next three years—and how much more expensive must new funding become before that choice changes?
| Input | Assumption |
|---|---|
| Existing loan | €900,000; 6% fixed; maturity in month 9 |
| Common comparison basis | 36 months; a continuing €900,000 funding requirement |
| DM objective | Cost Optimization: minimise conditional interest cost |
| Repayment | Bullet: principal repaid in full at maturity |
| Market basis | An illustrative EUR curve, shared by all alternatives |
| Two what-if tests | An additional 1 and 5 percentage points on new funding |
These results come from a local run of the structural calculation engine used by the available DM integration, with illustrative inputs. They have been independently recalculated. They are not current bank quotations or a saved LIVE report from a customer account. “Conditional cost” means the result depends on the stated assumptions; it is not a promise of future savings.
1. Base case: refinance earlier, with a shorter fixed-rate period
The model evaluates 19 eligible choices: refinancing now or in six months, for two, five or seven years, at a fixed rate, a floating rate or a 70% fixed / 30% floating mix; plus waiting until maturity and then using rolling one-year floating funding. All replacement loans are bullet loans. We also evaluate three reference policies from the structural engine.
| Strategy | Timing and structure | 36-month conditional interest | More than DM |
|---|---|---|---|
| DM selection | Now; two-year fixed, followed by modelled refinancing | €72,041 | — |
| A | Month 9: five-year fixed | €107,603 | €35,562 |
| B | Month 9: five-year 70% fixed / 30% floating | €106,106 | €34,065 |
| C | Month 3: seven-year fixed | €95,365 | €23,324 |
DM selects immediate refinancing into a two-year fixed-rate loan. The illustrative curve produces an initial fixed coupon of approximately 2.497%. The old 6% interest stops when the loan is replaced. Under A and B, the company continues paying it for nine months; under C, for three months.
The conditional advantage over the cheapest reference policy, C, is €23,324. Against A, it is €35,562. Neither amount is a demonstrated net saving: different fees, early-repayment compensation and other contractual costs could reduce or eliminate the advantage.
The shorter loan does not disappear from the calculation
The selected loan matures in month 24, while the comparison continues to month 36. The engine includes subsequent one-year floating funding for the remaining period. Both the early and later refinancing paths therefore cover the full three years. The funding requirement remains €900,000 throughout.
| What the company gains | What it still has to manage |
|---|---|
| Lower conditional cost in the base case | Access to replacement funding in month 24 |
| Five- or seven-year fixed funding under the reference policies | Longer contractual certainty, at a higher interest cost within this 36-month window |
| A common principal and comparison horizon | The €900,000 debt remains; costs after month 36 are outside the comparison |
The selected objective is Cost Optimization. Lower cost does not automatically mean lower refinancing risk. Policies A, B and C are the structural engine’s reference policies; they are not the separate 100% fixed, 100% floating and 70/30 reference paths in Track lifecycle.
2. What if new funding costs an extra percentage point?
We keep the same curve, the existing 6% coupon, principal and maturity. We add one percentage point to every new and subsequent funding arrangement. The spread does not apply to the existing contract. We rerun the selection rather than assume the original choice remains preferable.
| Strategy | Base: 0 pp | Spread: +1 pp | Increase |
|---|---|---|---|
| DM selection | €72,041 | €99,041 | €27,000 |
| A: 5-year fixed at maturity | €107,603 | €127,853 | €20,250 |
| B: 5-year 70/30 at maturity | €106,106 | €126,356 | €20,250 |
| C: 7-year fixed in month 3 | €95,365 | €120,115 | €24,750 |
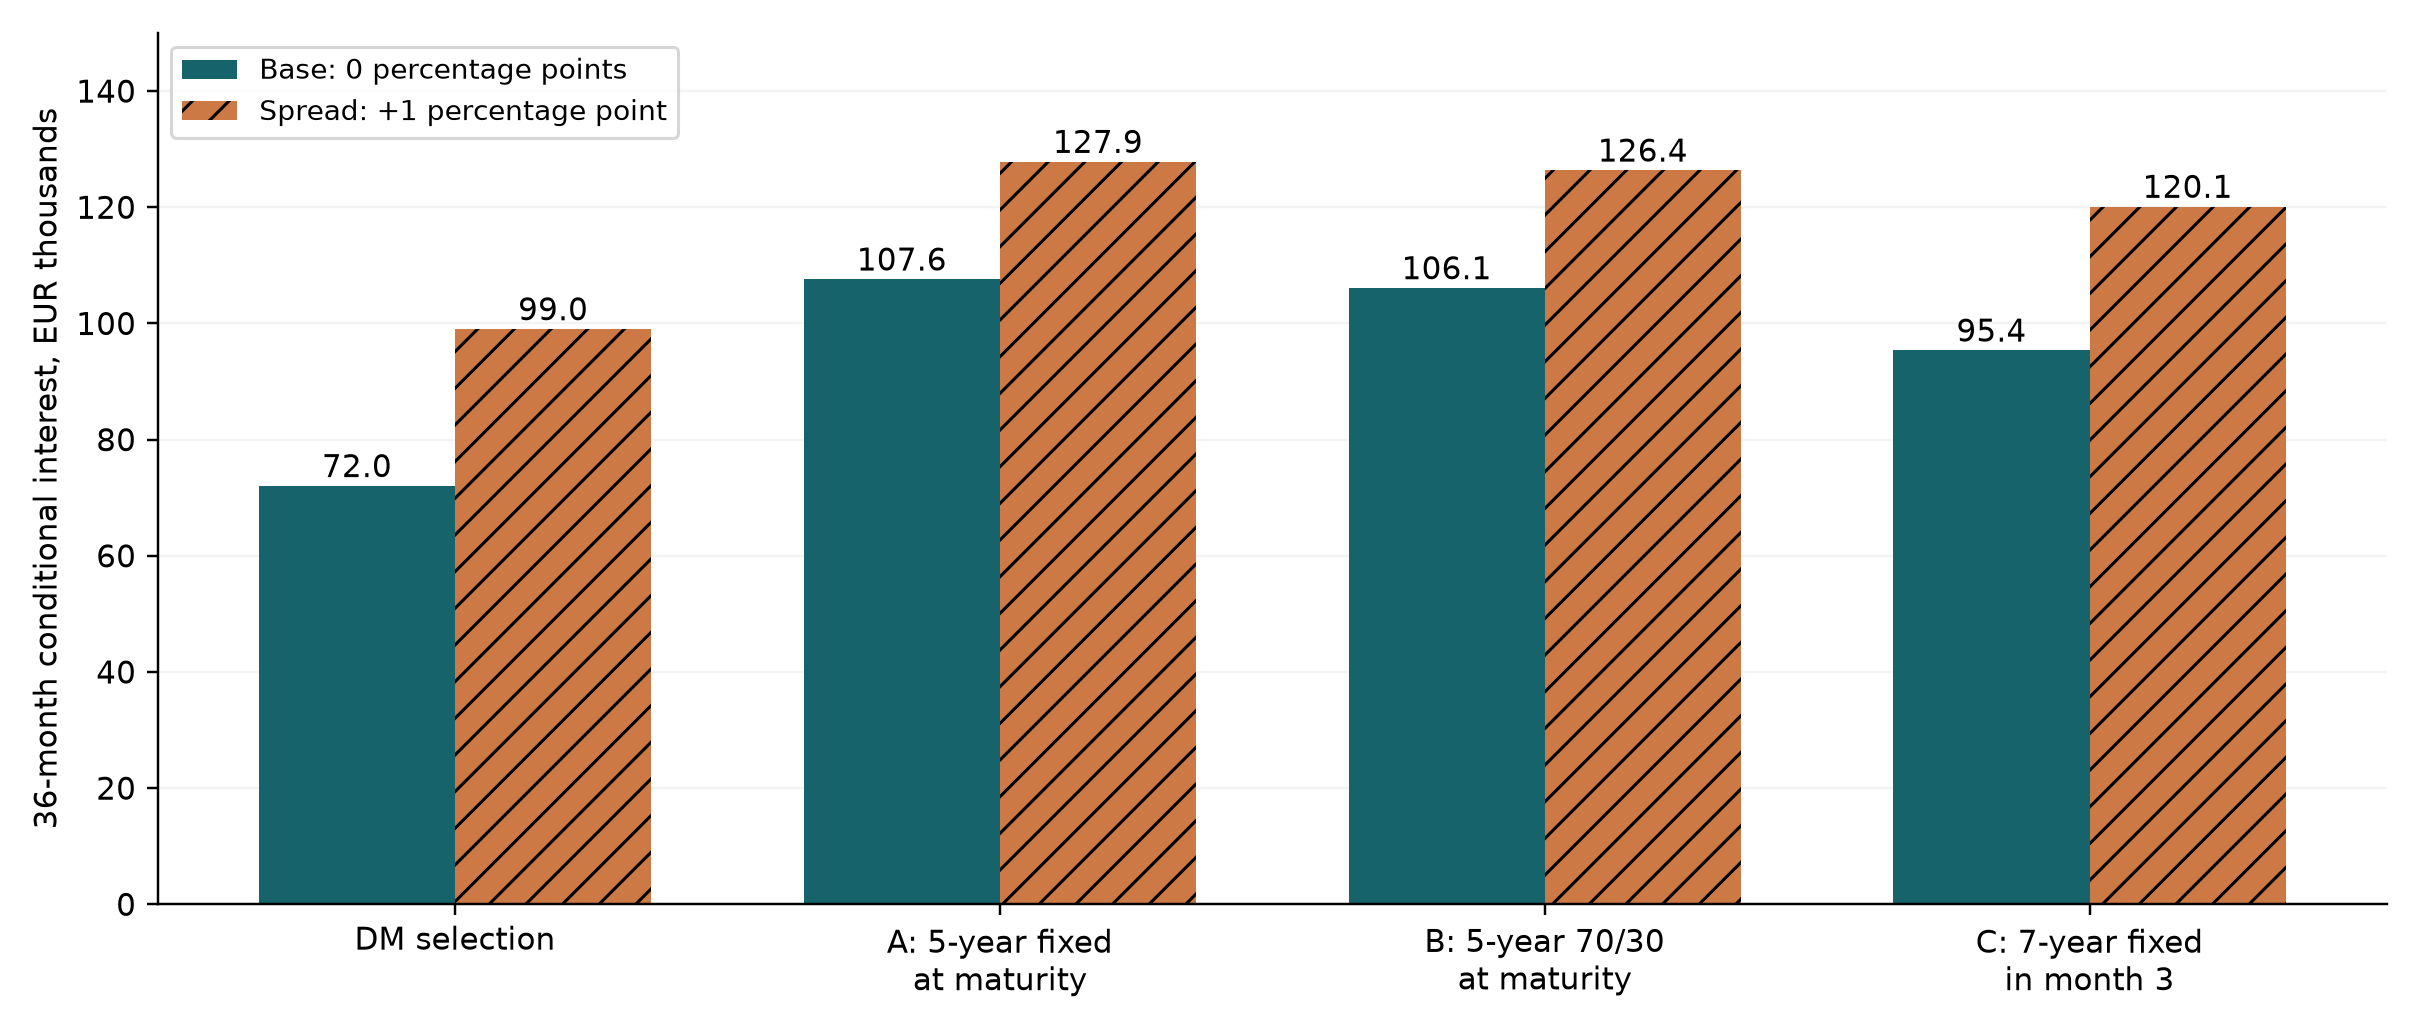
The choice holds: refinance now, for two years, at a fixed rate. The initial coupon rises to approximately 3.497%, and conditional cost increases to €99,041. The advantage over C narrows to €21,074, but remains positive.
The same spread does not create the same total increase. Immediate refinancing bears it for all 36 months: €900,000 × 1% × 3 = €27,000. A and B bear it for 27 months, adding €20,250. C bears it for 33 months, adding €24,750. Timing changes the sensitivity to funding costs.
3. What if the spread rises by five percentage points?
We return to the base case and apply a total five-percentage-point spread to new funding. This is a separate severe stress test—not another five points on top of the previous one, and not a market forecast. The existing loan remains at 6%.
| Strategy at +5 pp | Conditional interest | More than the new DM choice |
|---|---|---|
| New DM choice: wait until maturity | €203,864 | — |
| Retain the original choice: two-year fixed now | €207,041 | €3,177 |
| A: 5-year fixed at maturity | €208,853 | €4,989 |
| B: 5-year 70/30 at maturity | €207,356 | €3,492 |
| C: 7-year fixed in month 3 | €219,115 | €15,251 |
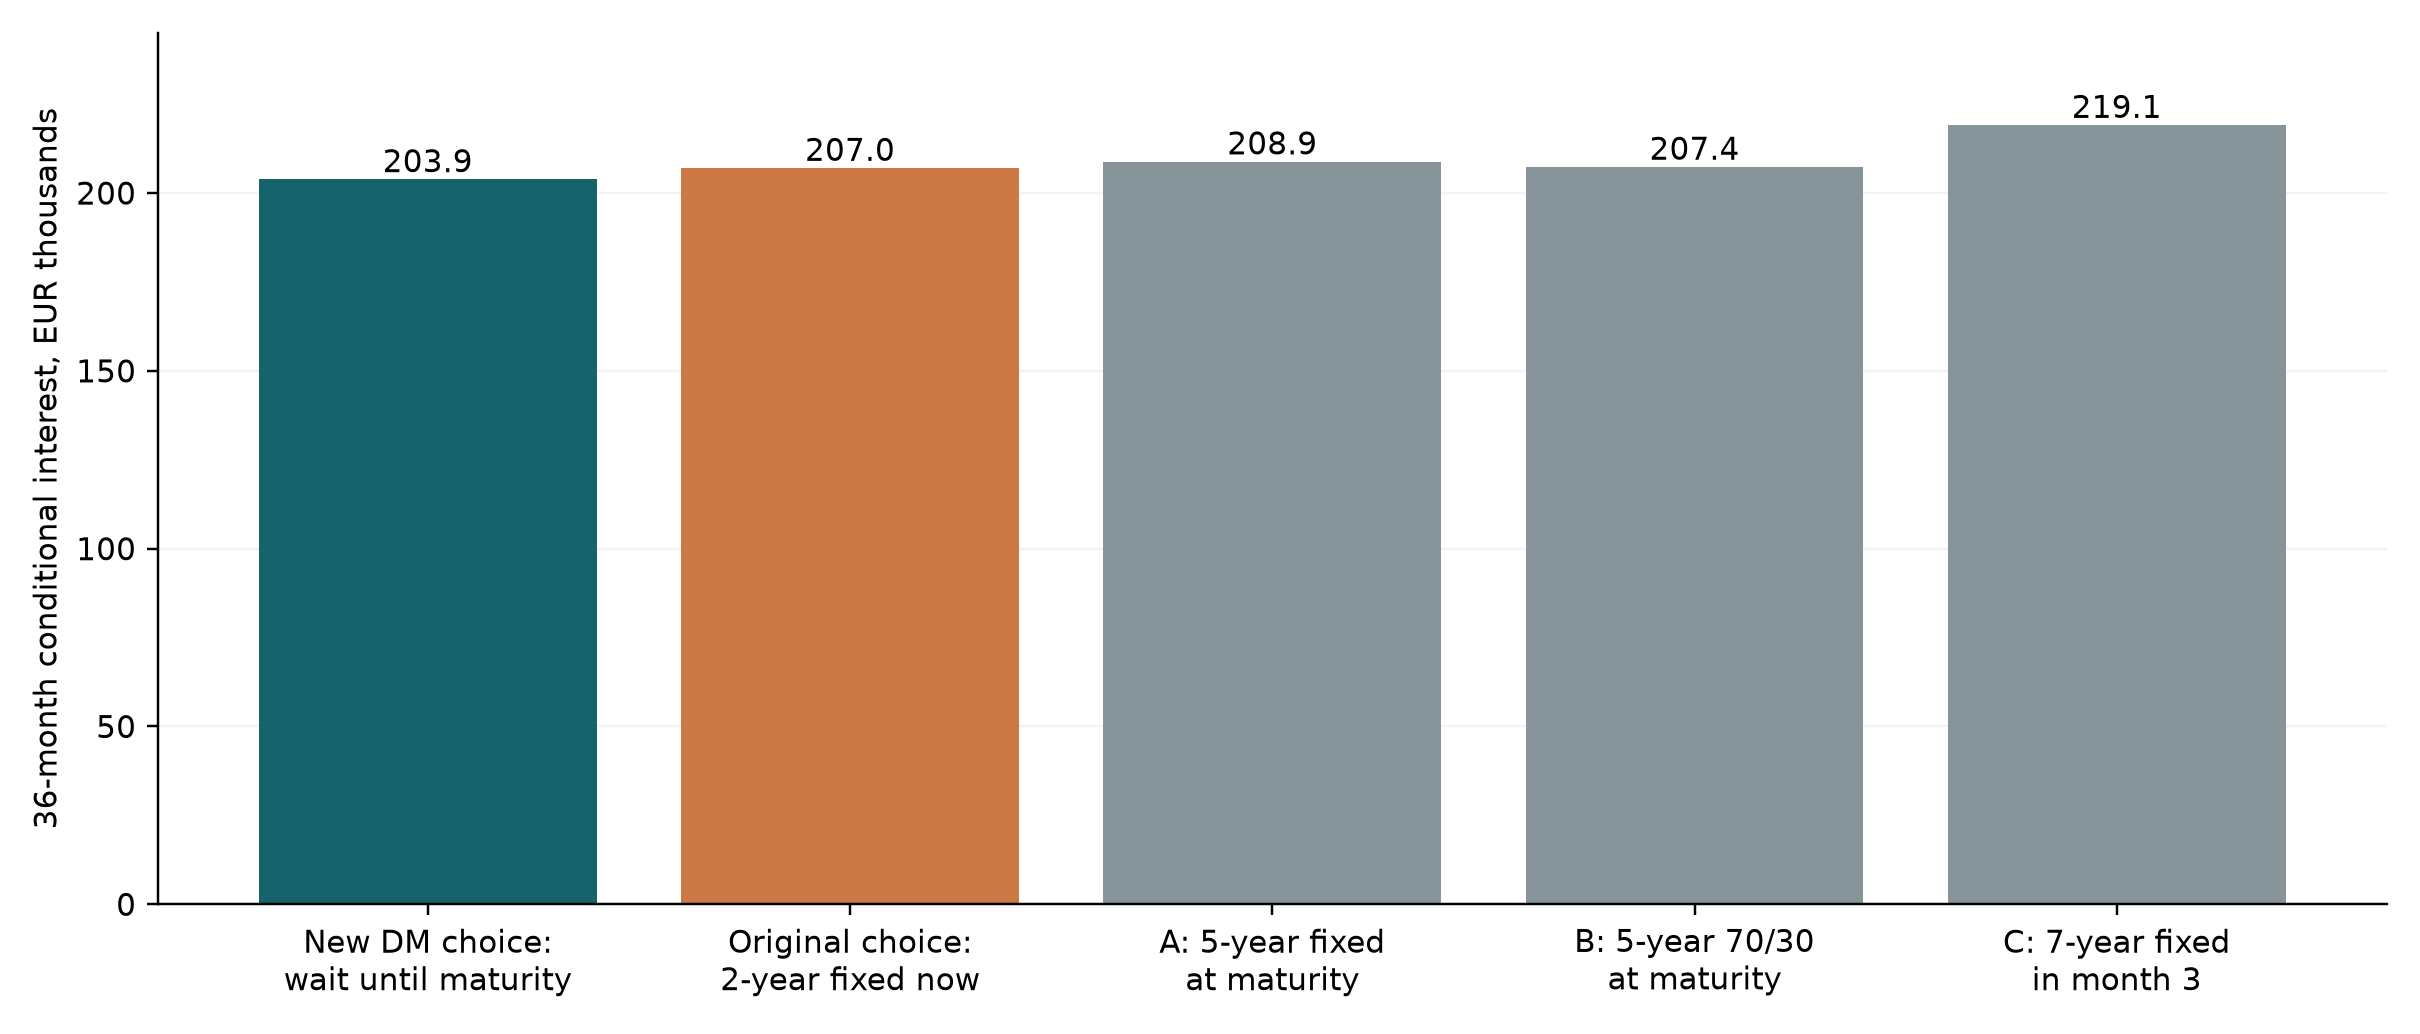
Here, the choice changes. Immediate two-year fixed funding would carry an initial coupon of approximately 7.497%, above the existing 6%. Under the minimum-conditional-cost objective, retaining the existing contract until month 9 and then following the model’s rolling one-year floating policy becomes cheaper.
The new choice costs a conditional €203,864—€3,177 less than retaining the original structure. Its advantage over the closest reference policy, B, is €3,492. That is a narrow margin: actual fees or differences between banks’ spreads could reverse the commercial decision.
Waiting is still a financing plan. Funding is needed in month 9, and the model’s rollover assumes continued market access. It is not a committed facility. Discussions with lenders must begin before maturity; the model’s choice concerns when the existing debt is economically replaced.
What this case demonstrates about Debt Management
| Test | Calculated choice | Decision insight |
|---|---|---|
| Base case | Two-year fixed now | Replacing the existing 6% loan early reduces conditional cost. |
| Spread +1 pp | Two-year fixed now | The choice holds, but its advantage narrows. |
| Spread +5 pp | Wait; then floating rollover | Higher funding costs change both timing and rate structure. |
This is the value of testing a decision across alternatives. With the principal and horizon held constant, DM connects the existing contract, replacement date, tenor, rate structure and subsequent funding requirement. The what-if tests show when the initial choice holds and when it changes.
From a model result to an executable decision
The finance team checks eligibility and selects Cost Optimization. It reviews the proposed actions, conditional costs and sensitivities, then incorporates actual bank spreads, fees and early-repayment restrictions. The team must establish whether the preferred structure is executable before committing to it. A saved decision can support subsequent reviews in Track lifecycle. Confirmation updates the model; it does not execute a bank transaction.
Explore the Corporate Debt Management Platform and its example reports to see how inputs, alternatives and decisions are recorded.
Method and limits
Illustrative curve. Continuously compounded EUR zero/spot rates are 2.00% at one year, 2.50% at two years, 3.00% at five years, 3.20% at seven years and 3.50% at ten years. These are not bank coupons. The engine linearly interpolates rates, including from the origin node of zero years and 0%, and derives discount factors. Fixed coupons use quarterly par pricing; floating cash flows use quarterly forwards from the same curve.
Spread and funding conventions. Spreads of 0, 100 and 500 basis points apply to all replacement and subsequent funding from its start date; 100 basis points equals one percentage point. Accrual uses months divided by 12. Early refinancing immediately replaces the old loan: there is no prefunding cash balance. Amounts are in EUR, calculated without intermediate whole-euro rounding and displayed to the nearest euro. Differences are calculated before display rounding.
What the metric excludes. The measure is undiscounted conditional interest over 36 months, not full contractual cost or present value. Fees, execution costs, taxes, early-repayment compensation and terminal mark-to-market values are excluded. Executable early repayment and access to replacement funding are assumed. Longer fixed-rate protection can have value outside this metric.
Scope of the result. The selected result is the minimum within the bounded set of 19 candidates, not proof of the best deal among all possible bank transactions. A, B and C are evaluated separately on the same pricing basis. Initial LIVE source assessments support fixed- or floating-rate bullet instruments with 6–36 months remaining; this illustrative loan fits those instrument and maturity conditions. The synthetic curve is not presented as governed market data for a production LIVE assessment.
Calculation checks. A local CFSE V4 run with the DM objective-selection layer, using Cost Optimization, was checked against an independent interest cash-flow calculation. All 12 principal results and the revaluation of the original choice at +5 percentage points agreed within €0.10. This was not a new production customer-session test.
Corporate Debt Lab provides the platform discussed in this article. This illustrative case study was prepared with AI assistance.